Blog categorized as Guides
PAYG instalments are based on last year's income, so a genuine drop this year means overpaying — but varying the instalment down carries a real penalty risk if the estimate turns out to be significantly understated.
RBizz Team
13/08/2026 04:49 PM - Comment(s)
STP reporting is tied to each pay day itself, not a periodic deadline like BAS — and businesses often misjudge this because it feels like other, less time-sensitive obligations. This
RBizz Team
11/08/2026 12:34 PM - Comment(s)
The 5-year record retention rule sounds simple, but the clock starts from when you lodge the relevant return — not the transaction date — and some records (depreciating assets, CGT) need to be kept well beyond 5 years.
RBizz Team
10/08/2026 04:14 PM - Comment(s)
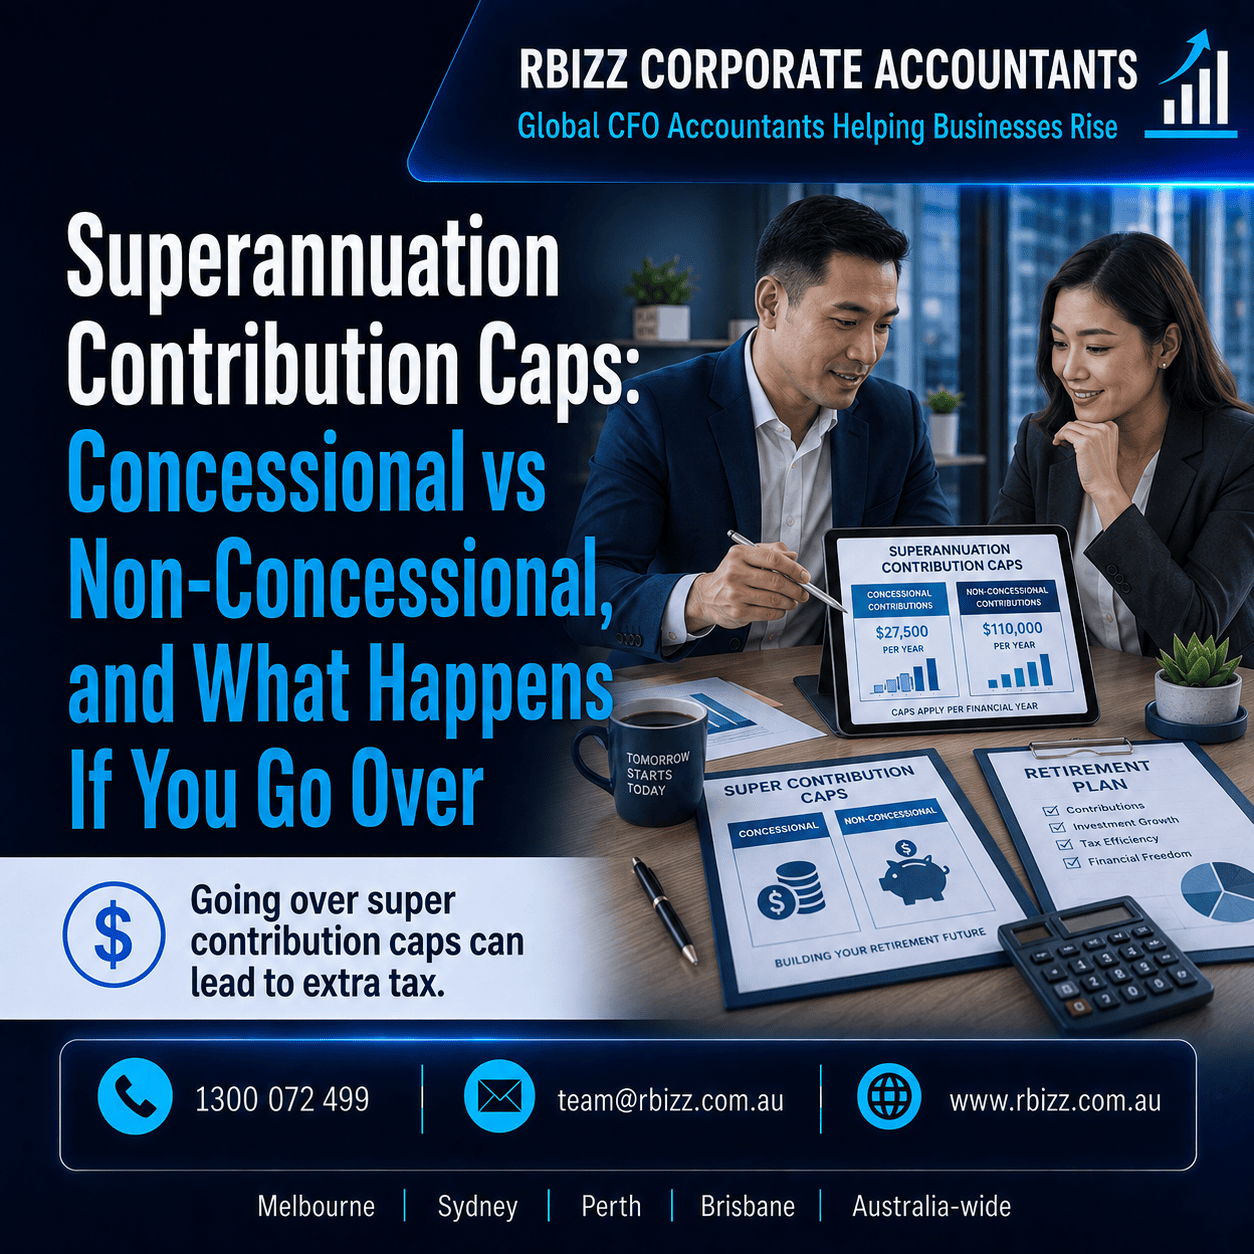
Business owners with irregular income are particularly likely to exceed a super contribution cap without realising, since multiple contribution sources can stack up unnoticed.
RBizz Team
07/08/2026 12:09 AM - Comment(s)
This offset is capped at $1,000 per person and calculated as a percentage of tax payable on business income — not a percentage of profit, which is the mistake that trips most people up.
RBizz Team
07/08/2026 12:08 AM - Comment(s)
Equity granted to employees isn't taxed like ordinary salary, and startups often assume any equity grant automatically qualifies for concessional treatment without checking the actual eligibility criteria.
RBizz Team
05/08/2026 05:13 PM - Comment(s)
The tax consequences of a business sale depend heavily on whether it's structured as a share sale or asset sale, and pre-sale restructuring can itself trigger unexpected tax events if not carefully planned.
RBizz Team
05/08/2026 04:06 PM - Comment(s)
Most government grants are assessable income by default, but specific programs can be legislated with different tax treatment — assuming either "automatically tax-free" or "automatically taxable" can lead to a real surprise at tax time.
RBizz Team
04/08/2026 12:04 PM - Comment(s)

Many commercial property owners never claim the full depreciation they're entitled to, simply because they don't have a proper schedule prepared by a quantity surveyor.
RBizz Team
04/08/2026 12:03 PM - Comment(s)

A business's first Australian tax season sets the compliance foundation for every year that follows, and international entrants often underestimate how differently registration, residency, and employment obligations work here.
RBizz Team
28/07/2026 02:52 PM - Comment(s)

Once combined income crosses a set threshold, an additional tax applies to concessional super contributions — and business owners drawing a mix of salary, dividends, and business income are more exposed than they often realise.
RBizz Team
23/07/2026 01:06 PM - Comment(s)

Buying equipment, vehicles, or technology is a normal part of running a business — but the timing and structure of that purchase can significantly affect how quickly you get a tax benefit from it. The instant asset write-off is one of the more well-known small business tax concessions, but it's a...
RBizz Team
23/07/2026 12:46 PM - Comment(s)
Tax obligations cluster at predictable points across the financial year, creating cash flow pressure that has nothing to do with profitability.
RBizz Team
23/07/2026 12:31 PM - Comment(s)

Many Australian businesses undertaking genuine technical problem-solving never realise they qualify for the R&D Tax Incentive, assuming it's only for labs and tech startups.
RBizz Team
22/07/2026 07:32 PM - Comment(s)

The tax consequences of selling or handing over a business depend heavily on timing and structure, not just the final deal. This guide covers the main succession pathways, how CGT concessions factor in, and why advance planning delivers far more options than a last-minute exit.
RBizz Team
22/07/2026 12:36 PM - Comment(s)

Consolidating a company group for tax purposes can simplify compliance and unlock benefits like loss offsetting, but the election is generally irrevocable and carries joint liability risk.
RBizz Team
20/07/2026 12:53 PM - Comment(s)

Realising a mistake after lodging a tax return is more common than most business owners think — and usually fixable, provided it's within the amendment period. This guide covers when amendments are possible, how the process works, and why acting early matters more than the mistake itself.
RBizz Team
17/07/2026 12:01 PM - Comment(s)
A tax bill you can't pay in full feels alarming, but the outcome depends almost entirely on how early you act. This guide covers what actually happens if payment is late, the ATO's payment plan options, and the steps to take before — not after — the deadline passes.
RBizz Team
15/07/2026 07:58 PM - Comment(s)
Tax season obligations differ significantly depending on whether you operate as a company, partnership/trust, or sole trader. This guide breaks down what each structure needs to prepare, watch out for, and lodge — with a practical checklist that applies across all three.
RBizz Team
09/07/2026 06:18 PM - Comment(s)
Tax may be boring, but smart use of tax planning is a superb way to help your company do more with your money.
RBizz Team
06/07/2026 10:44 AM - Comment(s)
Categories
- News Alerts
(103)
- Templates
(2)
- Guides
(288)
- Blogs
(174)
- Courses
(0)
- Health Checks
(0)
- Calculators
(0)
- Videos
(0)
- Compliance
(65)